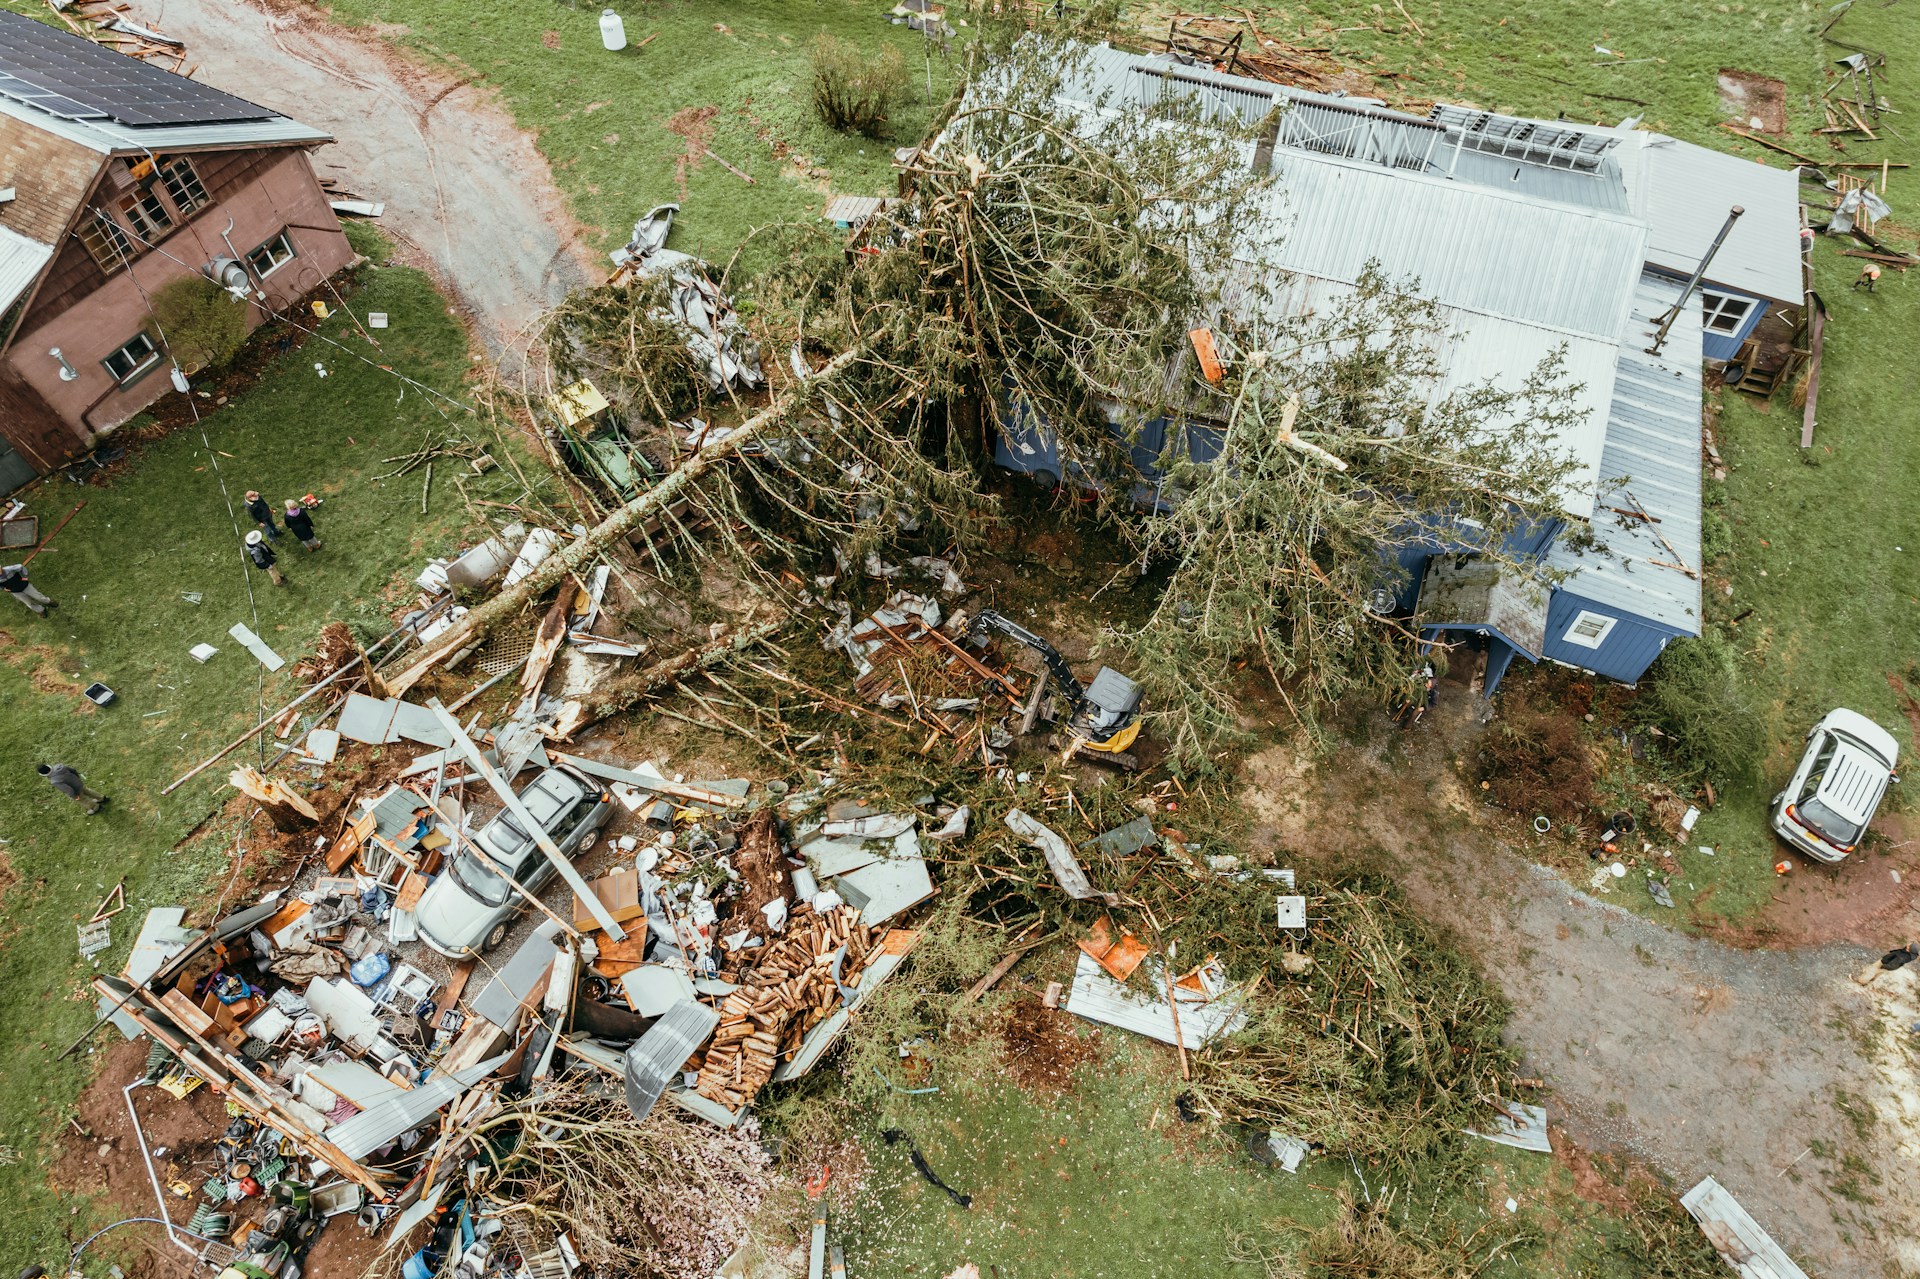
A home is considered high risk when an insurer expects it to produce more claims, or more expensive ones, than a typical home. That judgment usually comes from the property's location, its condition, or its claims history. For the homeowner, it can mean a higher premium, a larger deductible, narrower coverage, or a decision not to offer or renew a policy.
High risk doesn't mean uninsurable. Insurers weigh risk differently, and there are other routes to coverage when standard companies decline. Knowing which factors drive your premium also shows you which ones you can change.
What makes a home high risk to insurers
Each insurer weighs risk its own way, but most look at the same factors. The National Association of Insurance Commissioners (NAIC) lists location, claims history, rebuilding cost, the home's age and condition, fire protection, your deductible, and your insurance score among the main influences on a homeowners premium.
Insurers weigh these factors differently. Ask your insurer or agent which ones affect your quote.
Location is the one factor you can't change, and it's behind many high-risk ratings. Coastal homes face hurricane wind and storm surge, homes near wildland face wildfire, and homes in hail-prone areas face roof claims. The NAIC also points to wider pressures that raise premiums generally, including more frequent catastrophes, higher reinsurance costs, and rising repair and construction costs.
Insurers also pay close attention to roof age and condition. An older roof can lead to a surcharge, more limited roof coverage, or a decline. Our article on roof requirements that affect your coverage explains what insurers commonly look for.
Claims history and the CLUE report
Many insurers check the Comprehensive Loss Underwriting Exchange (CLUE), a claims database run by LexisNexis Risk Solutions that lists claims filed on a home over the past seven years. You can request a free copy of your own report once a year and dispute any errors. If you're buying a home, you can ask the seller to request the home's report and share it, which can show past water or roof claims.
Credit-based insurance scores
Where state law allows, insurers may look at your credit history when you apply for or renew a homeowners policy. Some states limit or prohibit this, so ask your insurer or your state insurance department how it works where you live. If an insurer takes an adverse action based on credit information, the Fair Credit Reporting Act requires it to tell you and to name the credit bureau that supplied the information. You can then get a free copy of your report and correct any errors.
Coverage gaps that often affect high-risk homes
A higher premium doesn't always mean broader coverage. These gaps come up most often for high-risk homes:
- Flood: standard homeowners policies exclude flood. Coverage comes from the National Flood Insurance Program or a private flood insurer.
- Earthquake: usually excluded and sold separately. See do I need earthquake insurance?
- Percentage deductibles: hurricane, wind, or hail deductibles may be a percentage of the dwelling limit. A 2% deductible on a home insured for $350,000 is $7,000.
- Building code upgrades: rebuilding to current codes can cost more than the policy pays unless it includes ordinance or law coverage.
- Wear and tear: damage from gradual deterioration, such as a slow leak or an aging roof failing, is generally not covered.
- Water damage limits: some policies cap water or mold claims. Our article on water damage caps explains how they work.
For a fuller list, see understanding coverage gaps in your homeowners policy.

Where to find coverage if standard insurers decline
If you've received a non-renewal or been turned down, start by finding out why. An independent agency can check several insurers at once, since each has its own appetite for risk. If standard companies still decline, these are the main options.
Availability and terms vary by state and insurer. Confirm the details with your insurance professional.
According to the NAIC, 33 states have some form of FAIR plan. These plans generally provide coverage for the dwelling, with belongings and other structures often available only as add-ons, while liability and loss-of-use coverage generally aren't offered. Some homeowners on a FAIR plan buy a separate policy to fill those gaps.
For what to do after a non-renewal letter arrives, see navigating non-renewal notices. For more on specialty markets, see understanding high-risk property insurance and how to find it.
How to lower the premium on a high-risk home
- Fix what the insurer flagged. If a decline or surcharge cites the roof, wiring, or plumbing, repairing it and documenting the work gives you something concrete to take back to the insurer.
- Add mitigation features. Impact-rated windows, storm shutters, a stronger roof, monitored alarms, and automatic water shutoff valves may qualify for discounts with some insurers. Ask which features yours recognizes and what proof it needs.
- Choose your deductible carefully. A higher deductible lowers the premium, but on a high-risk home it's the amount you're most likely to pay.
- Keep small losses off your record. Paying for minor repairs yourself can protect your claims history.
- Shop again at renewal. Insurers' appetite for risk changes, and an independent agent can compare several companies at once.
Getting high-risk homeowners insurance
IZC's licensed specialists can help homeowners compare coverage from the insurance companies IZC works with, including for homes that have been surcharged, declined, or non-renewed. Before you request a quote, have your roof age, details of any recent updates to the home's systems, and any non-renewal letter ready.
Start Your Quote Today
Our licensed specialist will search for the best insurance quotes and will email you when ready.